Tax
Receiving your tax assessment: what you check and what you send us
After filing comes the assessment, in the canton of Zurich as an assessment decision and an assessment order. Compare it with your return and send it…
annyway GmbH · Published: September 2026
For each property you choose again every year: the flat-rate deduction or the actual costs. Deductible is what preserves the value, not what increases it. For the allocation to work, invoices need a few details.
For each property held as private assets, you choose again in every tax period: the flat-rate deduction or the actual costs. In the canton of Zurich, the flat rate for cantonal and municipal taxes is 20 per cent of the imputed rental value or the gross rental income, regardless of the age of the building. For the direct federal tax it is 10 per cent if the building is no more than ten years old at the start of the tax period, otherwise also 20 per cent.
An example: with an imputed rental value of CHF 24’000 and an older building, the flat rate is CHF 4’800. If you carried out maintenance work for CHF 15’000 in the same year, deducting the actual costs pays off. There is no flat rate for properties used wholly or mainly for business.
Deductible is what preserves the value of the property: repairs, replacement with equivalent items, service contracts, property insurance and management by third parties. In condominium ownership, contributions to the renovation fund are included. Investments for energy saving and environmental protection, demolition costs for a replacement building and work on listed buildings are treated like maintenance costs.
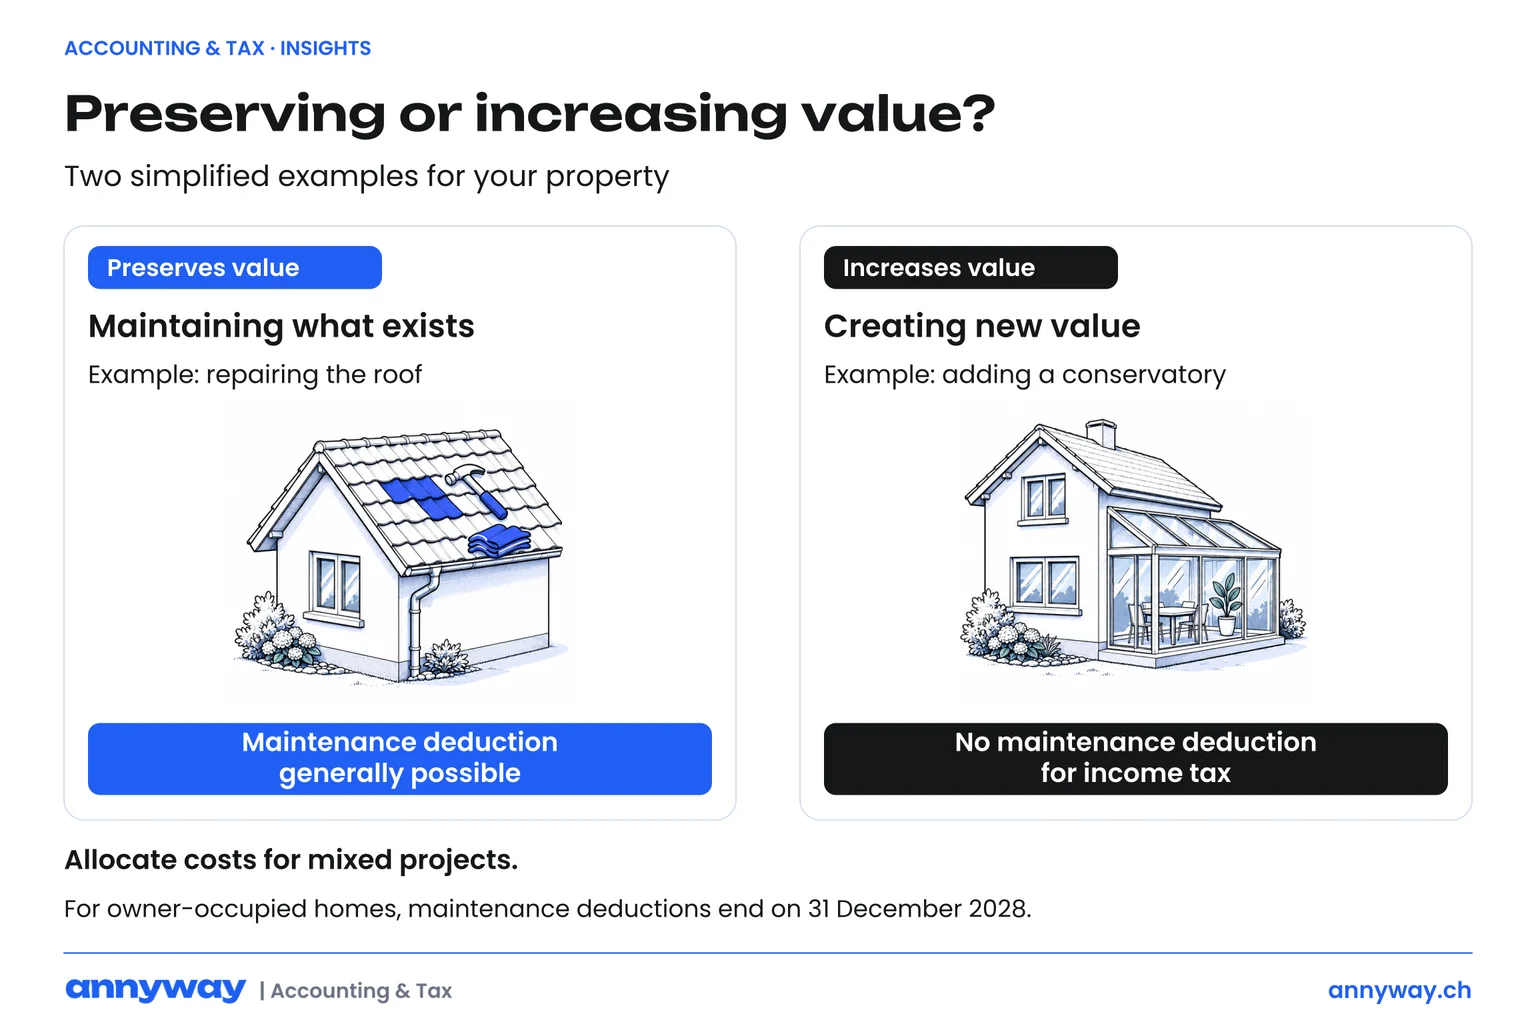 Image created with AI
Not deductible is what increases the value, such as a converted attic or a new conservatory. Keep these receipts anyway: when you sell, they count as investment costs and reduce the property gains tax. If a conversion includes both, the tax office splits the costs, in the canton of Zurich according to its own allocation catalogue.
Whether an invoice counts as maintenance depends on its content. For the allocation to work, every invoice should contain these details:
If you received subsidies or insurance payments for work, state them. They reduce the deductible amount.
In September 2025, the people and the cantons approved the abolition of the imputed rental value. The Federal Council has set the entry into force for 1 January 2029. Until the end of 2028, today’s rules apply, including the maintenance deduction. After that it no longer applies to owner-occupied properties. For rented properties it remains. If you are planning larger work, it is worth discussing the timing with us.
Many cantons stagger the flat rate by the age of the building, as the Confederation does. There are also cantonal differences in energy-saving measures and in splitting mixed work. If your property is outside the canton of Zurich, we clarify the rules for that canton.
We sort your invoices, compare the flat rate with the actual costs and choose the higher deduction for each property. You calculate the indicative price for your tax return in the tax finder.
Tax
After filing comes the assessment, in the canton of Zurich as an assessment decision and an assessment order. Compare it with your return and send it…
Tax
If your GmbH or AG pays you a dividend, it shows up in your private tax return under income and assets. From a 10 per cent…
Tax
For your private tax return we need your documents and the letter with your access details. We prepare the return, you check and approve it. On…
In a short conversation we clarify what you need and what to expect. Free and without obligation.