Tax
Receiving your tax assessment: what you check and what you send us
After filing comes the assessment, in the canton of Zurich as an assessment decision and an assessment order. Compare it with your return and send it…
annyway GmbH · Published: September 2026
If your GmbH or AG pays you a dividend, it shows up in your private tax return under income and assets. From a 10 per cent shareholding the dividend is only partly taxed, and you reclaim the withholding tax.
A dividend is resolved by the general meeting on the basis of the company’s annual accounts. Before the money reaches you, the company deducts 35 per cent withholding tax and pays it to the Federal Tax Administration. With a dividend of CHF 20’000 you therefore receive CHF 13’000, and CHF 7’000 goes to the federal government as withholding tax.
In the list of securities (Wertschriftenverzeichnis) you declare the full dividend, in the example CHF 20’000, not just the amount paid out. With this declaration you reclaim the withholding tax. The tax office credits it to you. If the dividend is missing from the return, this claim can be lost.
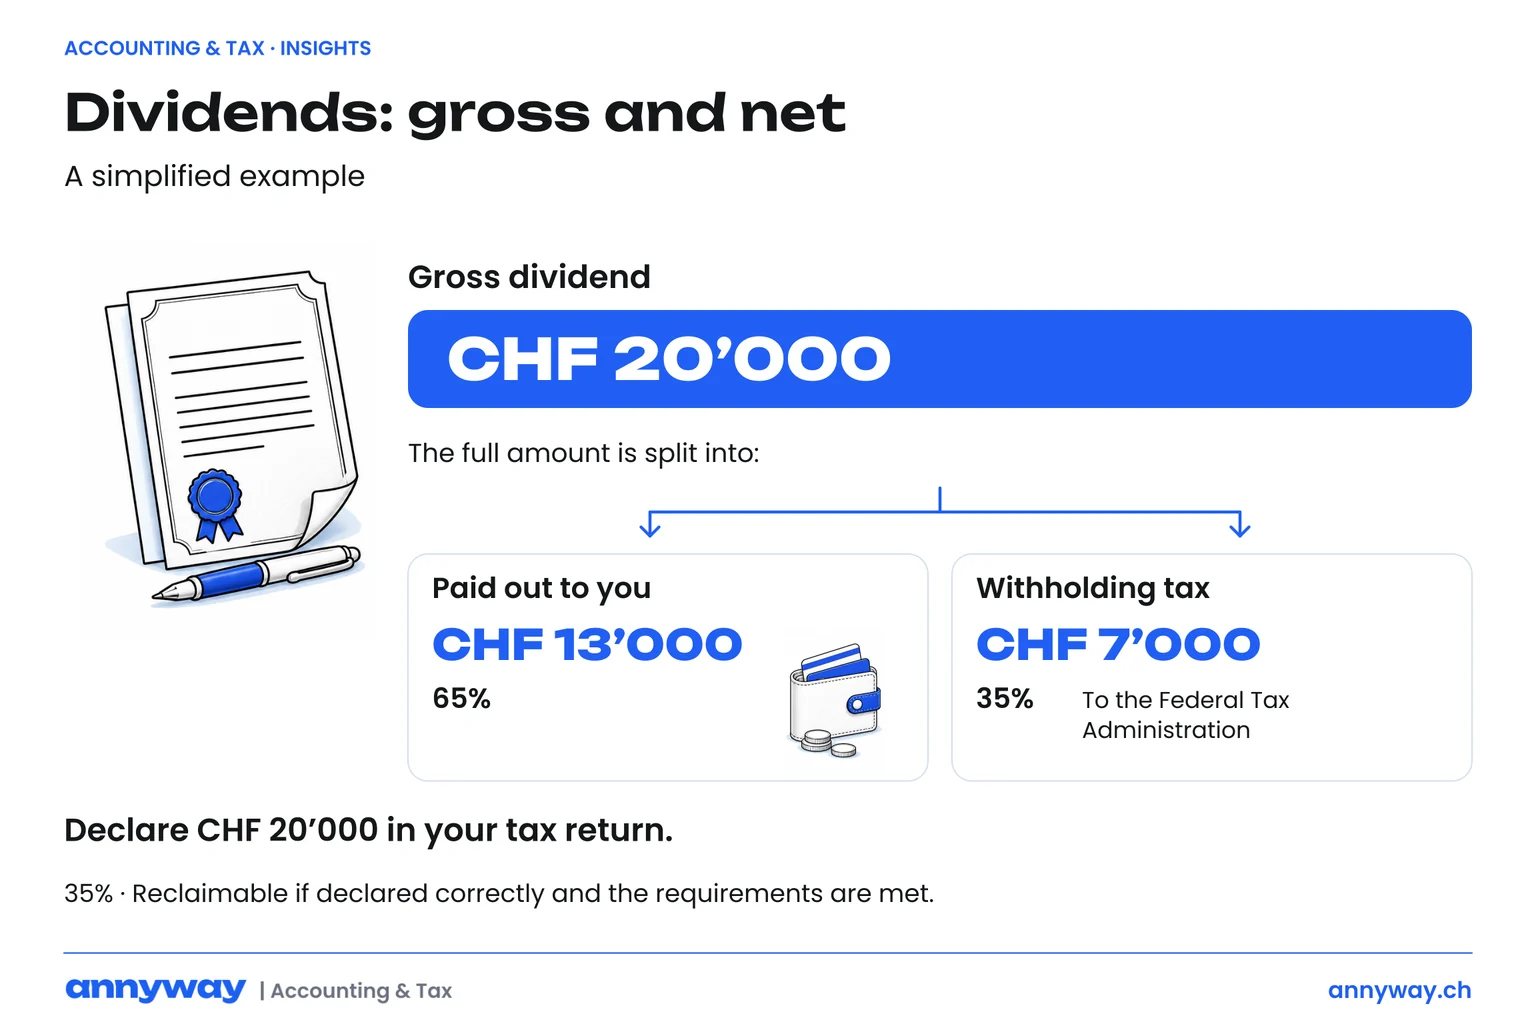 Image created with AI
If you hold at least 10 per cent of the share capital, the dividend is only partly taxed as income:
| Tax | Taxable share | With a CHF 20’000 dividend |
|---|---|---|
| Direct federal tax | 70% | CHF 14’000 |
| Cantonal and municipal taxes, canton of Zurich | 50% | CHF 10’000 |
The other cantons set their own share, at least 50 per cent. If your shareholding is below 10 per cent, the whole dividend is taxable. You reclaim the withholding tax on the full gross amount, provided you declare the dividend properly.
Your shares in the company also belong in the list of securities. For shares without a stock exchange price, the tax authorities set the tax value on the basis of the company’s annual accounts. This is another reason why the annual accounts should be finished before the private return is prepared.
Whether salary or dividend, and how to justify payments between you and the company, is covered in the article Separating private and business.
With us, your company’s annual accounts, the withholding tax settlement and your private tax return come from one source. That way the figures match on both sides. Request a first consultation.
Tax
After filing comes the assessment, in the canton of Zurich as an assessment decision and an assessment order. Compare it with your return and send it…
Tax
For each property you choose again every year: the flat-rate deduction or the actual costs. Deductible is what preserves the value, not what increases it. For…
Tax
For your private tax return we need your documents and the letter with your access details. We prepare the return, you check and approve it. On…
In a short conversation we clarify what you need and what to expect. Free and without obligation.